

A few years back, digital banking was mostly about checking account balances or making the occasional transfer through a mobile app. However, today customers expect more from banks, essentially being able to do all their transactions from the comfort of their home or office. Banks have had to rethink their delivery financial services, and few have embraced that shift as comprehensively as NCBA Group.
Over the past decade, the lender has steadily expanded beyond traditional banking to build one of Africa’s largest digital financial ecosystems. With its portfolio stretching from mobile lending and savings to overdrafts, payments, transaction banking and digital banking platforms serving customers in several African countries.
The latest rollout of NCBA NOW and ConnectPlus in Uganda and Rwanda is a clear indication of where the bank is heading. Rather than introducing standalone digital products, NCBA is expanding a banking ecosystem designed to give customers secure, convenient and always on access to financial services.

Banking built around the customer
The biggest shift in banking over the last few years has not been technology itself but changing customer expectations.
Retail customers expect banking to work as easily as the other digital services they use every day. Business owners want to authorize payments while on the move, monitor cashflow in real time and access banking services without having to visit a branch.
NCBA says those changing expectations shaped the development of both NCBA NOW and ConnectPlus. For individual customers, NCBA NOW brings together everyday banking into a single mobile platform. Customers can transfer money, pay bills, buy airtime, manage payment cards, monitor transactions. They can also access an expanding range of digital financial services through an interface designed to simplify routine banking.
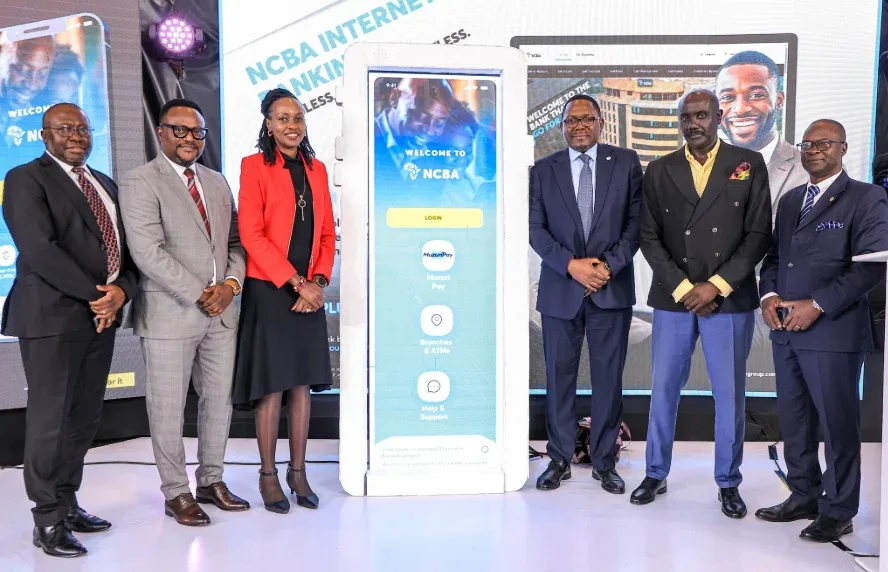
Speaking during the launch in Kampala, NCBA Bank Uganda Chief Executive Officer Mark Muyobo said the platforms were developed after listening to customers and understanding how the way people live and work continues to evolve.
Giving businesses more control
Businesses are no longer looking for platforms that simply process payments. They need systems capable of managing liquidity, supporting payroll, integrating with enterprise software. They should also be able to facilitate international transactions and give finance teams visibility over multiple accounts in real time.
That is the role NCBA expects ConnectPlus to play. The platform brings together account services, payments, collections, liquidity management, trade finance and host-to-host integrations within a single digital environment.
Businesses can initiate domestic and international payments, manage supplier settlements, process payroll and monitor cash positions. They can also generate detailed financial reports without having to utilize multiple systems.
For companies that operate in multiple markets, this means faster decision making and more control over daily financial operations.
Raising the bar for transaction banking
NCBA became the first bank in East Africa to deploy a cloud-based corporate banking platform. They replaced traditional banking technology with a cloud-native architecture built on microservices and open banking APIs.
While much of that happens behind the scenes, the impact is visible to customers. Transactions are processed faster, new services can be introduced more quickly and businesses are able to connect banking services with their own financial systems more efficiently.
The architecture also gives NCBA greater flexibility to respond as customer needs evolve. This allows the bank to launch new cash management and transaction banking products in a fraction of the time required by conventional banking systems.
Security
As more financial services move online, security has become one of the defining factors in how customers choose their banking partners.
ConnectPlus incorporates multi-layered security controls, configurable approval workflows and role-based access permissions. This allows organizations to determine who can initiate, review and authorize transactions.
These governance features reduce operational risk while giving businesses confidence that their financial information and payments remain protected.
NCBA has indicated that the same principles underpin its wider digital ecosystem, where reliability, security and customer trust continue to guide product development.
A complete financial ecosystem
The launch of NCBA NOW and ConnectPlus builds on foundations the Group has spent years putting in place. Today, NCBA serves more than 70 million customers through its banking subsidiaries and fintech partnerships.
Products such as M-Shwari, Fuliza, MoKash, MoMoKash, M-PAWA and LOOP have changed how millions of Africans save, borrow and make payments.
Across Uganda, Rwanda, Tanzania and Côte d’Ivoire, MoKash, MoMoKash and M-PAWA have reached a combined 35 million customers, disbursing more than US$2 billion in loans since launch.
In Kenya, M-Shwari has served more than 30 million customers, extending over US$6 billion in loans while helping millions develop a savings culture. Fuliza now processes more than four million transactions every day and has disbursed more than US$25 billion, giving customers access to short-term credit whenever they need it.
Those numbers tell a bigger story which is that NCBA is no longer simply a bank with digital channels. It has evolved to become a financial services provider whose products reach customers through multiple digital and corporate banking platforms across several African markets.
A regional strategy taking shape
Launching NCBA NOW and ConnectPlus simultaneously in Uganda and Rwanda demonstrates that the Group’s digital strategy extends beyond individual markets.
Businesses increasingly operate across borders, while customers expect a consistent banking experience regardless of where they live or work. Building digital platforms that can scale across multiple countries gives NCBA an advantage as regional trade and cross-border commerce continue to grow.
The strategy also supports wider efforts to deepen financial inclusion by making formal banking services more accessible to everyone. From individuals, entrepreneurs and businesses that increasingly rely on digital channels for their financial needs.
Digital banking continues to evolve, and customer expectations will keep changing with it. The introduction of NCBA NOW and ConnectPlus is less about adding two more products to the market and more about the direction the Group has chosen to take.
The investment reflects a belief by NCBA that banking should be available wherever customers are. Enabling them to adapt quickly to changing business needs and provide the security and reliability people expect when managing their money.